Swiss Regulator Clears First Retail Bitcoin ETF
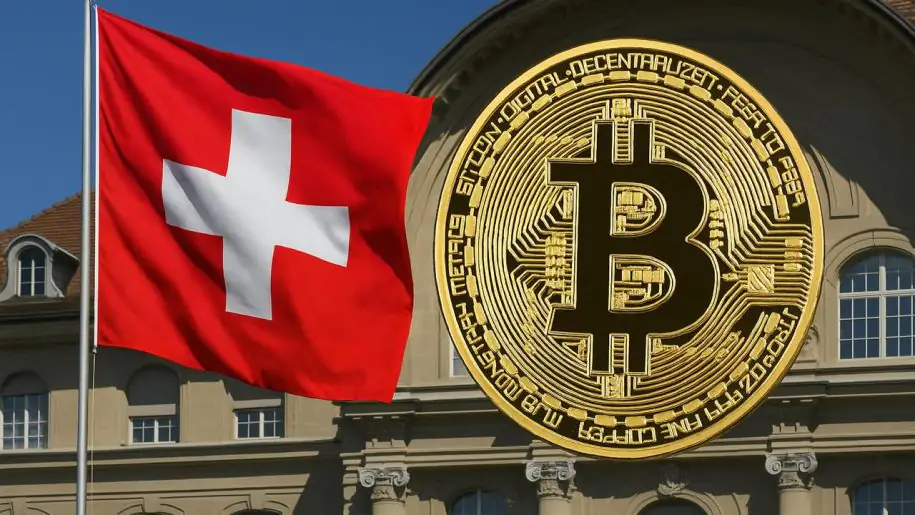
Swiss retail investors will be able to buy a fund that holds Bitcoin directly after the Swiss Financial Market Supervisory Authority (FINMA) approved the country’s first Bitcoin ETF on 20 October. To approve it, the regulator exempted the fund from the risk-diversification rules that normally govern Swiss investment funds.
FINMA did not name the provider, the fee or a listing date, though it said other fund providers have already filed or announced applications. The fund will enter a market where more than 200 crypto ETPs already trade on SIX Swiss Exchange, so its case rests on what a fund structure offers that those products do not.
What FINMA approved, and the rule it set aside
In its 20 October announcement, FINMA classified the ETF as an “other fund for alternative investments” with a specific risk. Swiss law uses that category for higher-risk strategies such as hedge funds, and FINMA said the fund documents must highlight and explain the risks clearly.
The crypto fund FINMA authorised in 2021 held a basket of cryptocurrencies and was open only to qualified investors. The new ETF holds a single asset and is open to retail buyers, a combination that required the exemption.
FINMA based that exemption on Bitcoin’s long trading history and high trading volume relative to other cryptocurrencies. Both are liquidity arguments: they show the fund can buy, value and sell its holdings efficiently. Neither addresses concentration, which is what diversification rules exist to limit. A holder of the fund carries Bitcoin’s full price risk, and FINMA itself warned that invested capital may lose a significant part of its value.
How the fund compares with the ETPs already on SIX
Bitcoin exposure on a Swiss exchange is not new. SIX listed the first crypto ETP, a 21Shares basket product, on 22 November 2018. Its May 2026 crypto products report counted 215 crypto ETPs among 374 listed crypto products.
crypto ETPs listed on SIX Swiss Exchange in May 2026, out of 374 crypto products in total
SIX’s guide to the segment sets out the legal difference. A Swiss ETP must be fully collateralised, and an independent third party holds the collateral so it remains available if the issuer becomes insolvent. A Swiss ETF goes a step further: its assets are segregated by law and stay outside the provider’s estate in a bankruptcy. ETP investors rely on the collateral arrangement working as designed, while fund investors hold a claim on assets that are legally separate from the provider’s own.
FINMA also pointed to conduct rules at the point of sale. Firms offering the ETF must follow the Financial Services Act (FinSA), including clear risk warnings and a suitability assessment, which FINMA said gives investors more protection than buying cryptocurrency directly. The comparison there is with direct ownership rather than with ETPs, since FINMA’s reminder covers every crypto-based financial instrument.
| Swiss crypto ETP | Swiss Bitcoin ETF | |
|---|---|---|
| Legal form | Collateralised exchange-traded security | Investment fund under Swiss fund law |
| If the provider fails | Investors rely on collateral held by an independent third party | Fund assets are segregated from the provider’s estate |
| Diversification rules | Fund diversification rules do not apply | Apply in principle; FINMA granted an exemption |
| Trading on SIX | Since November 2018 | Listing date not announced |
| Fee example | 0.21% standard management fee on the 21Shares Bitcoin Core ETP | Not disclosed |
Neither route gives the investor a private key. Both deliver Bitcoin exposure through a brokerage account, so in both cases the coins sit with a custodian, and the fund’s legal protection is only as strong as the custody chain behind it.
Where the fund’s Bitcoin would be held
FINMA tied the approval to its January 2026 custody guidance. Under that guidance, Swiss collective-investment assets must generally sit with a Swiss custodian bank. The bank may delegate safekeeping to another institution if that institution is subject to equivalent prudential supervision and protects cryptoassets in bankruptcy.
The fund
Assets segregated from the fund provider
Swiss custodian bank
Generally required for Swiss fund assets
Delegated custodian
Possible if supervised and bankruptcy-protected
The requirement narrows the risk without removing it. If safekeeping is delegated abroad, the protection depends on that jurisdiction’s insolvency law working as described, which is why the prospectus should name any sub-custodian and where it operates. The guidance also flags operational threats such as cyberattacks and weak protection of private keys, risks that legal segregation does not cover.
Why Switzerland’s route differs from the EU’s
SIX notes that the EU’s UCITS framework, which governs mainstream European ETFs, does not allow cryptocurrencies as underlying assets and requires broad diversification. European investors therefore reach Bitcoin mainly through exchange-traded notes and other ETPs. The United States has permitted spot Bitcoin ETFs since January 2024.
Switzerland now offers both: collateralised ETPs and a single-asset Bitcoin fund of a kind EU fund rules do not permit. FINMA’s statement that further providers have applied points to more Swiss Bitcoin ETFs rather than a single test case.
What the listing documents need to show
The counter-argument is cost. Full collateralisation already limits issuer risk in Swiss ETPs, and those products have years of trading on SIX. If the first ETF charges noticeably more than existing Bitcoin ETPs, legal segregation may not justify the premium for investors who buy and hold through a bank or broker.
The first SIX listing notice and prospectus will settle that question by disclosing the ongoing charge, the custodian and any delegated custodian, and the creation and redemption terms. A fee at or below the 0.21% standard rate 21Shares lists for its Bitcoin Core ETP would make the fund a direct competitor. A fee well above it would leave fund-law protection as its only selling point. Over the following months, approvals for the other applicants FINMA mentioned would show whether Bitcoin ETFs become a product category in Switzerland or remain a single listing.
This article is provided for informational purposes only and does not constitute financial, legal or investment advice.


Kosta has reported on cryptocurrency markets and blockchain infrastructure since 2020, bringing over six years of hands-on experience in the crypto industry built through daily tracking of markets, trends, and emerging blockchain developments. Specializing in Bitcoin on-chain analysis, institutional ETF flows, and digital asset price action, his work at Coindoo has been cited by other news agencies and consistently covers market developments with a focus on data-driven reporting across Bitcoin, Ethereum, Solana, and XRP. Over the years, Kosta has contributed to multiple crypto media outlets in different regions, authoring over 6,000 articles across the sector. His reporting spans cryptocurrency markets and the broader fintech industry, tracking not only price action but also the technological and regulatory forces shaping the ecosystem. To support his analysis, Kosta actively leverages on-chain data and metrics from leading platforms such as Santiment, Glassnode, and CryptoQuant, enabling deeper, evidence-based market insights. He believes in the power of transparency and the data that underpins the blockchain ecosystem. His academic background in Marketing Management from Denmark further complements his analytical approach, adding a strong understanding of communication strategy and content positioning to his work.